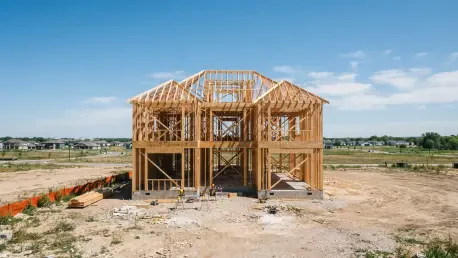
The United States currently averages fewer than three housing permits per one thousand residents, a figure that falls short of many regional growth projections. This data, emerging from a detailed analysis by the Lied Center for Real Estate at the University of Nevada, Las Vegas, highlights a persistent disconnect between the demand for shelter and the regulatory permissions required to build it. Across the nation, the housing shortage has evolved from a localized issue into a systemic hurdle that restricts economic mobility and increases the cost of living for millions. As of the current period in 2026, researchers Nicholas Irwin and Shawn McCoy have identified that national permitting activity has reached approximately 2.83 permits per 1,000 residents. This metric serves as a critical leading indicator, suggesting that the inventory shortages observed today are likely to persist because the pipeline for future construction remains constrained. The stagnation is particularly evident when comparing these figures to the higher growth benchmarks established just a few years ago. While some regions have managed to maintain momentum, the overall national decline of over four percent suggests that builders and local governments are struggling to find a sustainable equilibrium in a high-cost environment.
Rising Stars: The New Centers of Residential Construction
A distinct geographic shift is currently reshaping the map of American homebuilding, with a new tier of high-growth states emerging as the primary drivers of new inventory. South Carolina, Idaho, and North Carolina have successfully positioned themselves at the forefront of this trend, consistently outpacing the national average by significant margins. South Carolina leads the nation with more than six units permitted per one thousand residents, representing a notable five percent increase in activity over the previous reporting period. Similarly, Idaho has recorded a robust 6.4 units per thousand residents, particularly in expanding urban centers like Nampa, where the development of supporting infrastructure is moving in lockstep with residential growth. These states have demonstrated that it is possible to maintain a high volume of construction despite the broader economic headwinds that have slowed activity elsewhere. This proactive approach provides these regions with a critical inventory buffer that could eventually stabilize local housing costs and offer a more balanced market for prospective buyers.
The success of these leading states is largely attributed to the synergy between robust local economies and a regulatory climate that prioritizes the efficient issuance of building permits. By streamlining the approval process and maintaining favorable environments for developers, these states allow builders to respond more quickly to market signals. Economists observe that this combination is essential for addressing the supply-side deficiencies that define the modern housing crisis. In contrast to more restrictive markets, these high-growth regions are effectively creating a surplus of “future intent” through their permitting volume. This forward-looking strategy ensures that as the population grows, the housing stock remains flexible enough to accommodate new residents without triggering the extreme price volatility seen in coastal or stagnant inland markets. Furthermore, the ability of these states to outpace national averages suggests a template for regional success that involves long-term planning and a commitment to maintaining building momentum even when national sentiment appears cautious.
Regional Shifts: The Sun Belt Slowdown and the Nevada Gap
For several years, the Sun Belt served as the primary engine for American housing production, but the latest data from 2026 suggests that this momentum is experiencing a cooling period. States like Texas, Arizona, and Utah, which were once the epicenter of a historic building boom, are now seeing their permitting rates fall behind previous record highs. While these states still account for a large absolute number of new permits, the deceleration in their growth rates is a significant development for the national real estate landscape. This shift is particularly concerning because these regions continue to attract thousands of internal migrants fleeing higher-cost coastal markets. If the rate of production continues to falter while the population increases, the relative affordability that once defined the Sun Belt could vanish, replaced by the same inventory crunches that have plagued the Northeast and California for decades. This trend indicates that even the most traditionally pro-growth regions are not immune to the cooling effects of broader economic pressures.
Nevada currently serves as a stark outlier and a cautionary tale regarding the dangers of falling behind household growth projections. The state has recorded a staggering twenty-nine percent drop in its permit-to-resident ratio, which represents the most significant decline in the nation during this period. Current projections suggested that Nevada would need to permit over twelve thousand units to keep pace with demand, yet actual figures have fallen well below nine thousand units. This substantial deficit creates a scenario where the creation of new households is vastly outpacing the construction of new roofs. When supply cannot meet the basic needs of a growing population, the long-term outlook for affordability becomes increasingly bleak. For residents in the Silver State, this production gap suggests that rent and home prices will likely face sustained upward pressure for the next several years. This situation underscores the fact that without a consistent and predictable pipeline of new permits, even states with ample land and a history of growth can find themselves trapped in a cycle of deepening housing scarcity.
Market Pressures: High Interest Rates and Builder Hesitation
The construction industry is navigating a difficult landscape defined by several macroeconomic factors that have dampened the enthusiasm for new residential projects. Mortgage rates have remained persistently high, hovering around 7.3 percent, and are expected to stay above the seven percent threshold through 2027. These elevated rates create a double-edged sword for the housing market: they reduce the purchasing power of potential homeowners while simultaneously increasing the cost of capital for developers. When the cost of financing a new project rises, the profit margins for builders are squeezed, leading many to delay breaking ground on larger developments. This hesitation is reflected in the nationwide decline in total permits, which fell by over five percent month-over-month in the most recent data set. The resulting atmosphere is one of caution, where builders are more focused on selling existing inventory through concessions and price adjustments rather than committing to the long-term risk of new, large-scale construction starts.
Beyond the challenges of the financial markets, developers are also struggling with the rising costs of essential inputs such as land, specialized labor, and raw materials. These expenses make it increasingly difficult for new builds to compete with the prices of existing homes, further discouraging new activity. Consequently, builder confidence has been shaken, leading to a shift in strategy where many companies are relying on incentives like mortgage rate buy-downs to attract buyers to their current listings. This shift suggests that the current volume of permits, while still substantial in some areas, may not immediately translate into active construction sites. Instead, permits are increasingly serving as a placeholder for future intent, allowing builders to position themselves for a potential market recovery without committing to immediate expenditures. Until the cost of development stabilizes and interest rates become more favorable, the national permitting rate is likely to remain below the levels necessary to fully resolve the affordability crisis, keeping the supply of new homes at a premium.
Strategic Reform: Diversifying Supply and Policy Solutions
An analysis of the current permit composition reveals a continued reliance on traditional suburban-style development, which may not align with the evolving needs of the American population. Currently, approximately sixty-four percent of all permitted units are single-family homes, while only a small fraction—roughly 3.5 percent—are classified as “missing middle” housing, such as duplexes and small multi-family complexes. This concentration on single-family units often limits the density required to make urban housing more affordable and accessible. However, there is a growing consensus among policymakers regarding the necessity of reform to address these imbalances. Legislative sessions across various states have begun to focus on simplifying the building process and encouraging the construction of Accessory Dwelling Units. By allowing for more flexible housing options in established neighborhoods, local governments can provide a much-needed boost to the total housing stock without requiring the massive infrastructure investments associated with new suburban sprawl.
The current permitting trends observed in 2026 will directly dictate the housing landscape of the next several years, as there is typically a lag of eighteen to twenty-four months between the issuance of a permit and the completion of a home. This temporal gap means that the decisions made by local planning boards and private developers today will determine the availability and pricing of housing through 2028. To bridge the gap between supply and demand, a concerted effort is required to move past the regulatory barriers and community opposition that often stall development projects. Forward-looking strategies must involve not only the promotion of large-scale residential projects but also the diversification of housing types to include more high-density and affordable options. Ultimately, solving the affordability crisis was never a matter of just building more homes; it required building the right types of homes in the places where they were most needed. As the market moves forward, the states that prioritize these strategic reforms will be the ones best prepared to offer their residents a stable and accessible path to homeownership.