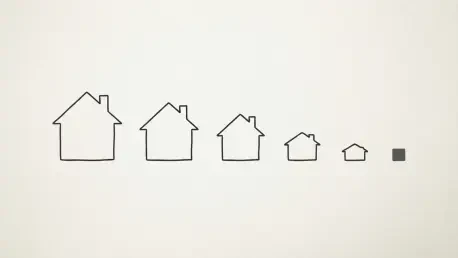
Families across South East Queensland are discovering that the traditional Australian dream of a backyard and multiple bedrooms has rapidly transformed into a luxury that is increasingly out of reach for the average household budget. Only a few short years ago, a weekly rent of five hundred dollars could comfortably secure a spacious four-bedroom house, yet as of mid-2026, that same financial commitment often provides nothing more than a modest one-bedroom apartment. This precipitous drop in purchasing power represents a loss of three full bedrooms in less than five years, forcing a massive demographic shift where growing families are squeezed into high-density living spaces once reserved for single professionals. The speed of this contraction has caught many by surprise, creating a volatile environment where the demand for affordable housing far outstrips the available inventory. A shrinking pool of private rental stock further complicates this crisis, leaving many residents with few options but to significantly downsize their expectations or relocate.
Economic and Regulatory Drivers of Market Contraction
Financial Pressures: Managing High-Value Assets
The primary mechanism driving the reduction in available rental properties is the staggering increase in holding costs faced by individual investors, who have historically provided the bulk of the region’s housing. Recent data from industry analysts at Herron Todd White indicates that maintaining a standard investment property valued at one point three five million dollars in Brisbane now requires an annual out-of-pocket expenditure of approximately thirty thousand four hundred dollars. This calculation assumes a standard interest rate of six point five percent, which has become the baseline for many mortgage holders in the current economic climate. For many “mum-and-dad” landlords, this level of negative cash flow is simply unsustainable, leading to a mass liquidation of assets. Instead of providing homes for renters, these owners are opting to sell their properties to owner-occupiers or move their capital into more liquid and less regulated financial instruments that offer a more predictable financial future for their families.
Policy Impact: Federal and State Regulatory Reforms
Beyond basic maintenance, the fiscal landscape has been further strained by state land tax surcharges and federal reforms to negative gearing. For investors subject to these surcharges, the annual “cash bleed” can escalate to over forty-five thousand dollars, creating a financial burden that few middle-class families can afford to subsidize for an extended period. These pressures have led to a dramatic exit of Self-Managed Super Funds from the market, with participation in new house-and-land estates plummeting from twenty-one percent to a mere three percent in the period leading up to mid-2026. Furthermore, new buyers of established homes are now restricted from offsetting investment losses against their primary income, a change that has significantly disincentivized the purchase of existing properties for rental purposes. This removal of the financial cushion has ensured that the properties sold by exiting landlords are rarely replaced by new rental units, further tightening the rental market.
Market Structural Shifts and Supply Challenges
Interest Rates: Adapting to the New Economic Normal
Economists and industry experts are increasingly warning that the current affordability crisis is not a temporary anomaly but rather a fundamental shift toward a “new normal” in the regional property sector. With interest rates projected to remain within the three point five to four percent range for the foreseeable future, the era of ultra-low borrowing costs that fueled the previous decade of growth is firmly in the past. This structural change means that the financial models used by many investors are no longer functional, as the cost of debt continues to exceed the rental yield in many prime locations. Despite government efforts to assist first-home buyers, mortgage demand has actually decreased by twenty-two percent, and the state faces a shortfall of nearly thirty thousand homes relative to National Housing Accord targets. The current affordability levels are the worst recorded since the turn of the millennium, reflecting a deep-seated imbalance between earnings and the cost of shelter.
Strategic Solutions: Restoring Balance to the Rental Market
The resolution of the South East Queensland rental shortage ultimately hinged on a dual approach of tax reform and targeted construction stimulus. To address the shrinking rental pool, the regional housing strategy moved away from punitive regulations on landlords and toward a model that prioritized the rapid expansion of housing stock through streamlined development. It became clear that resolving the crisis required a fundamental shift in perspective, where the investor class was viewed as a necessary partner in providing essential infrastructure rather than a target for tax revenue. Planners focused on reducing bureaucratic hurdles that slowed down the construction of diverse housing types, including medium-density developments. These proactive measures were taken to re-engage private savings by offering more favorable conditions for investing in new residential builds. This shift allowed the total volume of available units to increase, which naturally eased the upward pressure on weekly rents.