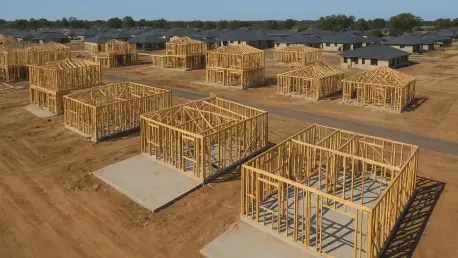
A critical shortage of residential construction has resulted in a $45 billion loss to the national economy while depriving the government of $11 billion in tax revenue. This stark reality underscores the widening chasm between the Albanese government’s ambitious National Housing Accord and the tangible output of the Australian building sector. To remain on track for the target of 1.2 million new homes over five years, the country needed to complete approximately 480,000 residences within the last two years. However, data from the Australian Bureau of Statistics confirms that only 355,817 homes were actually finalized, leaving a staggering deficit of nearly 130,000 units. This shortfall is not merely a matter of missed deadlines; it represents a fundamental failure to accommodate a rapidly growing population, driving up property prices and making homeownership an elusive dream for many. The stagnation in building activity reflects a broader crisis in the national infrastructure strategy that now requires an immediate correction.
Regional Disparities and State Performance
The burden of this construction slowdown is felt most acutely in the largest states, which are failing to meet their historical benchmarks and internal projections. Victoria and New South Wales, traditionally the primary engines of the national housing market, both recorded a notable decline in completions compared to the previous two-year window. In Victoria, while absolute volume remains high at over 112,000 new homes, the figures fell short of the 118,000 units built in the preceding cycle. This trend is particularly alarming given the state’s internal commitment to delivering 80,000 homes annually. Similarly, New South Wales saw its completions drop from 95,303 to 91,954, illustrating a systemic inability to scale up production in high-demand urban corridors. These declines in the nation’s most populous regions act as a heavy anchor, dragging down the national average and signaling that the regulatory and financial environments in these hubs are increasingly hostile to development.
Conversely, several other states have shown modest growth, providing a slight but insufficient buffer against the national downward trend. Queensland, Western Australia, and South Australia all recorded increases in building activity, with Queensland contributing nearly 69,000 homes and Western Australia exceeding 42,000. While these gains are encouraging, they are far from enough to compensate for the significant losses in the southeast. Meanwhile, smaller jurisdictions like the Northern Territory and Tasmania continue to face severe challenges, producing only 1,240 and 4,842 homes respectively over the same period. This fragmented landscape reveals that the housing crisis is not a uniform problem but rather a collection of regional bottlenecks. The disparity between states suggests that while some local governments are finding ways to streamline approvals, the lack of a cohesive national approach continues to hinder the overall pace of construction, leaving many Australians without viable options.
Economic Headwinds and Industry Barriers
The inability to meet construction targets has had profound economic consequences that extend well beyond the housing sector itself. Industry experts estimate that the current shortfall represents a $45 billion loss in broader economic activity, as the ripple effects of construction spending fail to penetrate local businesses and service providers. Furthermore, the shortfall has deprived the government of approximately $11 billion in tax revenue that would have been generated through stamp duty and Goods and Services Tax. This massive financial gap carries a heavy social cost, as these lost funds could have easily supported more than 43,000 essential workers, such as nurses and teachers, across the country. As the supply-demand imbalance worsens, Australian housing remains fundamentally unaffordable and inaccessible, particularly for vulnerable populations who are being systematically marginalized. The economic cost of inaction is now visible on the national balance sheet, affecting public services and fiscal health.
Small businesses, which constitute nearly 98% of the construction industry, are currently enduring what many leaders describe as death by a thousand cuts. These firms are grappling with an overwhelming regulatory burden, including recent federal changes to investor tax benefits and more stringent administrative requirements from the taxation office. For many builders, the increasing complexity of trust structures and credit card bans for tax payments have created a suffocating climate of uncertainty. This environment stifles the ability of small builders to survive, let alone ramp up production to meet federal targets. The combination of high compliance costs and shifting property investment settings has discouraged new builds, leading to a visible retreat of private investment from the residential market. Without significant structural reform to reduce these hurdles, the industry remains trapped in a cycle of low productivity, where the risks of taking on new projects often outweigh the potential rewards for smaller developers.
Strategic Imperatives for Stabilizing the National Market
Looking ahead to the window from 2026 to 2028, the construction sector must navigate a perfect storm of macroeconomic challenges that threaten to derail future progress. Persistent high interest rates have made financing more expensive for both developers and homebuyers, and the full weight of these monetary policies is only now beginning to manifest in completion data. Global supply chain disruptions, fueled by ongoing geopolitical instability, continue to drive up the cost of essential building materials, while a chronic shortage of skilled tradespeople extends project timelines indefinitely. Industry analysts warned that these headwinds were likely to produce even softer completion figures in the coming years unless there was a dramatic shift in policy direction. The current trajectory suggests that the target of 1.2 million homes is becoming increasingly a matter of political aspiration. Addressing these external pressures required a more resilient supply chain and targeted immigration policies.
To rectify these systemic failures, policymakers shifted their focus toward long-term structural reforms that prioritized deregulation and direct investment incentives. The government recognized that simply setting ambitious targets was insufficient without addressing the underlying costs of land acquisition and the inefficiencies of the planning system. Stakeholders advocated for a reduction in the tax burden on residential projects and a streamlining of the approval process to encourage a more diverse range of housing types. These measures were designed to restore confidence among builders and investors, ensuring that the period between 2026 and 2028 served as a turning point for the industry. By fostering a more supportive environment for small-scale developers and incentivizing the adoption of modern construction technologies, the nation sought to close the supply gap more effectively. Ultimately, the lessons learned from recent shortfalls underscored the need for a collaborative approach that aligned goals.