A historic gap in trade school enrollment during the post-GFC decade has left the modern housing market without enough senior site supervisors and lead plumbers. The United States residential construction sector is currently navigating a pivotal shift as the period of declining building costs appears to be coming to an end. After a three-year stretch where expenses per square foot saw a double-digit decrease, prominent industry leaders are now warning of a significant tightening in the labor pool. This transition marks a departure from the post-pandemic stabilization and suggests that homebuilders must brace for a new era of cost volatility driven primarily by a scarcity of skilled workers. While the cooling of material prices provided a temporary boost to builder margins, structural issues within the workforce are beginning to resurface. Large-scale developers are reporting that the “soft landing” of construction costs has stalled, with regional labor shortages becoming a tangible obstacle.
Industrial Competition: The Data Center Construction Surge
The rise of the data center industry, fueled by the global demand for artificial intelligence, has created a massive rival for construction resources. In just a few years, the ratio of spending on data centers compared to single-family homes has increased nearly sevenfold, pulling essential resources away from residential neighborhoods. This massive capital influx into the tech sector is not just a financial trend; it represents a direct physical competition for land and infrastructure. Tech giants are expanding their footprints at an unprecedented pace, often operating on timelines and budgets that traditional homebuilders cannot match. This growth creates a direct conflict for finite resources, particularly in high-growth regions. As these massive server farms rise, they consume the same concrete and electrical components that would otherwise be destined for the housing sector. Developers are seeing these shifts drive prices upward while complicating the logistics of site development in competitive hubs.
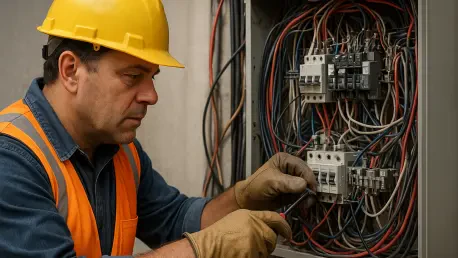
This competition is felt most acutely in the hunt for specialized tradespeople, such as electricians and HVAC technicians, who are indispensable for both housing and high-tech facilities. Because tech giants often have deeper pockets and offer higher wages, homebuilders find it difficult to secure the subcontractors necessary to keep residential projects on schedule. In regions where data centers are clustered, such as Northern Virginia, this tug-of-war leads to significant project delays and upward pressure on specialized labor wages. The complexity of modern data center cooling systems requires mechanical expertise, pulling the most skilled laborers away from domestic plumbing or heating installations. Consequently, residential developers must compete for a dwindling pool of talent, forcing a reevaluation of project timelines and cost structures. The shift represents a fundamental realignment of how skilled labor is allocated across the broader national economy today.
Demographic Erosion: Bridging the Generational Skills Gap
The homebuilding workforce is currently grappling with a dual-edged demographic crisis that threatens its long-term stability. A wave of retirements among the Baby Boomer generation is stripping the industry of its most experienced site supervisors and master tradespeople. This loss of institutional knowledge is difficult to quantify but easy to feel on the job site, as the veteran professionals who once managed complex builds leave the field. Unlike entry-level tasks, the nuances of managing a multi-unit housing development require years of hands-on experience. As these veterans exit, the quality of oversight often diminishes, leading to increased rework and slower inspections. The lack of a robust mentorship culture within the trades exacerbates this issue, leaving a void where there should be a steady transfer of expertise. Builders are struggling to find individuals capable of filling high-stakes supervisory roles, further extending the duration of standard residential builds.
Compounding this problem is a structural gap in the labor pipeline that dates back to the 2008 financial crisis. For nearly a decade following the housing market collapse, recruitment into the trades plummeted, resulting in a “missing generation” of mid-career professionals. Today, there are too few workers with ten to fifteen years of experience to step into leadership roles. While entry-level labor can be hired for basic tasks, the shortage of highly skilled plumbers and electricians remains a significant bottleneck. This middle-management vacuum means that even if a firm can hire enough apprentices, they lack the seasoned foremen necessary to direct them efficiently. Furthermore, the cultural push toward four-year university degrees has left the talent pool shallow. Addressing this gap requires more than just higher wages; it necessitates a rebranding of the construction industry to attract a new demographic of workers who can handle modern building and automated systems.
Migration Dynamics: Impacts of Shifting Workforce Flow
International migration has historically served as a vital valve for the construction industry, providing a steady stream of workers for the most physically demanding roles. With foreign-born workers making up a substantial portion of the total construction workforce, the industry is highly sensitive to shifts in immigration policy and net migration numbers. Recent data indicates a sharp decline in the number of new arrivals, a trend that is already beginning to manifest as tightness in specific regional labor markets. This reduction in the labor supply is occurring at the same time that immigration enforcement is becoming more prominent, further shrinking the pool of available workers. For homebuilders, this means that the era of abundant labor is likely over. As the supply of laborers willing to perform essential tasks like roofing and framing diminishes, builders are forced to either pay higher premiums or adopt new technologies to reduce their reliance on manual labor.
The impact of these migration shifts is not uniform across the country, creating a fragmented landscape for developers. In border states and major urban centers where construction relies heavily on migrant populations, the scarcity of labor has reached critical levels. This localized pressure forces contractors to bid against one another for the same small teams of framers and masons, leading to wage inflation that quickly eats into project margins. Moreover, the uncertainty surrounding long-term migration trends makes it difficult for firms to plan multi-year developments with cost certainty. To mitigate these risks, some larger homebuilders have begun exploring more permanent hiring solutions, including sponsoring visas for skilled tradespeople or investing in international recruitment programs. However, these efforts are often bogged down by bureaucratic hurdles. Without a predictable flow of labor, the industry remains vulnerable to sudden spikes in operational costs and project stagnation.
Strategic Evolution: Navigating a Permanent Talent Scarcity
The industry responded to these challenges by pivoting toward long-term structural solutions rather than temporary fixes. Builders who successfully navigated this period realized that the labor shortage was not a fleeting trend but a permanent fixture of the modern economic environment. By investing heavily in off-site prefabrication and modular construction, many firms managed to reduce their reliance on on-site manual labor while maintaining high quality standards. Additionally, the formation of deeper partnerships with local community colleges and vocational schools became a standard practice for securing a future talent pipeline. These initiatives focused on integrating technology, such as building information modeling and drone surveillance, to increase the efficiency of the existing workforce. Companies that prioritized employee retention through better benefits and career progression paths saw lower turnover and more consistent build times during the shifts.
Strategic shifts in the market emphasized total process integration and aggressive recruitment strategies to remain competitive. Developers looked toward vertical integration, bringing more specialized trades in-house to avoid the volatility of the subcontractor market. This approach allowed for better control over scheduling and helped buffer the impact of rising labor costs seen elsewhere in the industry. Furthermore, advocating for labor policies that recognized the critical role of migrant workers in the national infrastructure became essential for long-term health. Future considerations included the adoption of robotics for repetitive tasks, allowing the limited pool of skilled human workers to focus on complex problem-solving and quality control. By blending technological innovation with a focus on vocational prestige, the homebuilding sector overcame the bottleneck. Success in the 2026 to 2028 window depended on treating labor as a strategic asset.