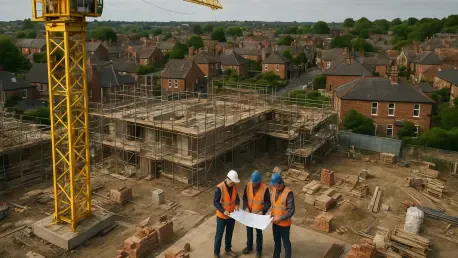
The introduction of this levy creates a significant sunk cost for smaller firms that played no part in historical safety failures but must now absorb the financial burden. This regulatory requirement, established under the Building Safety Act, serves as a cornerstone for a ten-year initiative designed to raise approximately £3.4 billion for remediating historical building defects. While the necessity of addressing past failures is undisputed among industry veterans, the current economic environment of 2026 adds layers of complexity to its execution. Residential developers are currently grappling with persistent material inflation and a labor market that remains tight despite broader economic stabilization efforts. Consequently, the levy is viewed not just as a safety measure but as a formidable financial obstacle that threatens the viability of mid-sized schemes. As the industry pivots toward these new standards, the focus remains on how to bridge the gap between safety and housing density.
Geographic Financial Scaling and Regional Burden
Regional Variances: The Weight of Project Location
The financial mechanics of the levy are fundamentally tied to geography, with rates determined by local market conditions and collected by local authorities to ensure regional relevance. By weighting the charge against average house prices, the government has created a highly stratified payment system that varies dramatically from one county to the next. For example, a development project located in a lower-value region like County Durham might see a relatively modest levy of approximately £12.70 per square meter of internal floor area. In stark contrast, a prime residential project in a high-demand borough such as Kensington and Chelsea could face costs exceeding £100 per square meter. This vast discrepancy means that developers must perform hyper-local financial modeling long before breaking ground. While the intention is to scale the tax relative to potential revenue, it places a unique strain on projects in areas where house price growth has decoupled from construction costs.
Economic Pressure: Assessing the Developer Financial Load
Beyond the raw numbers, the geographic scaling of the levy introduces a layer of unpredictability that can destabilize project financing during the early planning phases. Although the system seeks to align costs with the eventual sale value of the units, it frequently overlooks the varying profit margins inherent in different developer business models. Larger national firms may have the liquidity to absorb these regional spikes, but regional players often find their margins squeezed to the point of unviability. Furthermore, the administrative burden of calculating and negotiating these figures with local authorities adds another time-intensive step to the pre-construction timeline. This regulatory friction is particularly acute in secondary markets where land values are modest but construction costs remain high. The result is a development landscape where the feasibility of a scheme is determined as much by its postcode as by its design quality, forcing a rigorous re-evaluation of regional pipelines.
Strategic Adaptations and Project Viability
Design Efficiency: Maximizing Floor Space and Quality
In a direct response to the financial pressures of the levy, many developers are now fundamentally altering their design philosophies to preserve the economic viability of their schemes. A common strategy involves a meticulous focus on maximizing saleable floor area while aggressively minimizing non-revenue-generating spaces like large lobbies or wide corridors. While this approach helps maintain the necessary internal rate of return, there is a growing concern among urban planners that it could lead to a decline in the overall quality of modern living environments. For instance, the reduction of communal amenities and circulation spaces may help offset the levy, but it risks creating high-density blocks that lack the social infrastructure needed for long-term resident wellbeing. Additionally, some firms are intentionally scaling their projects back to just nine dwellings to avoid the ten-unit threshold entirely. This trend toward smaller, fragmented developments creates a systemic challenge for housing targets.
Land Strategy: Prioritizing Brownfield and Value Renegotiation
The secondary effect of the levy is a total shift in how land is valued and acquired across the English development sector. Developers are increasingly utilizing the 50% discount offered for qualifying brownfield sites to mitigate the levy’s impact, which has accelerated the trend toward urban regeneration and the repurposing of derelict industrial land. This incentive is a powerful tool for policy alignment, yet it simultaneously makes greenfield sites less attractive and harder to justify on a balance sheet. To further insulate themselves from these costs, many firms are entering into aggressive land value renegotiations with vendors, arguing that the levy acts as an unforeseen tax that must be deducted from the purchase price. These negotiations often lead to protracted delays in site acquisition, which can stall the commencement of new housing projects by several months. As land owners eventually adjust to this reality, the industry is seeing a more cautious approach to speculative development.
Regulatory Integration and Long-Term Implications
Compliance Management: Managing Exemptions and Gateway 2
Navigating the complexities of exemptions has become a specialized field within development consultancy, particularly regarding the role of housing associations. While these organizations are technically exempt to safeguard the delivery of affordable housing, the practical application often presents significant legal hurdles. Many affordable housing projects are delivered through joint ventures between non-profit associations and private developers. Current guidance indicates that if a joint venture is not fully owned by a qualifying housing association, it may lose its exempt status and become liable for the full levy amount. Simultaneously, the levy coincides with the stringent requirements of ‘Gateway 2’ overseen by the Building Safety Regulator. This regulatory checkpoint requires developers to submit comprehensive technical plans before construction begins. The intersection of these demands has created a new standard for project management where success is defined by navigating bureaucratic Gateways.
Future Perspectives: Balancing Safety and Housing Delivery
The development community ultimately adapted to these financial pressures by integrating the levy directly into their long-term feasibility models. It became clear that the most successful firms were those that prioritized brownfield regeneration and utilized advanced spatial planning to mitigate the added square-meter costs. Moving forward, developers looked toward standardizing safety-first designs that allowed for streamlined approvals, thereby reducing the overhead associated with regulatory delays. Proactive engagement with local authorities also proved to be a vital strategy for clarifying regional rate applications early in the design phase. For many, the next step involved investing in digital twins and sophisticated project management software to track compliance data with precision. This move toward a data-driven approach allowed the sector to move past the initial shock of the levy and toward a more resilient business model that secured high-quality, safe housing within a demanding framework.