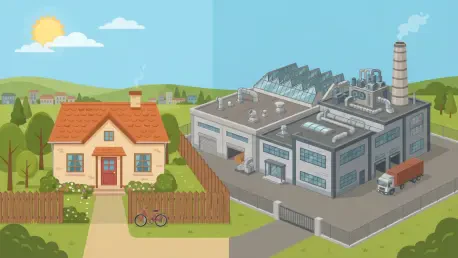
Asphalt shingle manufacturers are grappling with a market where year-to-date volumes have reached approximately 118 million squares, a significant decline from 2025 levels. This contraction illustrates a profound shift in the North American construction landscape as the industry maneuvers through the third quarter of 2026. While previous years were defined by post-pandemic recovery and high demand, the current environment is shaped by a noticeable divergence between different construction segments. Macroeconomic pressures, such as fluctuating interest rates and varying levels of capital investment, have fundamentally altered shipment volumes for asphalt-based products across the continent. These changes are forcing stakeholders to reevaluate their market strategies as the residential and nonresidential sectors move in opposite directions. This divergence highlights a two-speed economy where the resilience of large-scale infrastructure projects stands in stark contrast to the challenges faced by individual homeowners and residential developers.
Challenges in the Residential and Remodeling Sectors
The residential roofing market has experienced a significant downturn, with asphalt shingle shipments in the United States dropping by 13% compared to the third quarter of the previous year. This decline is not an isolated event but rather an acceleration of a downward trend that intensified as 2026 progressed, leaving year-to-date totals down by more than 7.3%. Manufacturers are closely monitoring these volumes, as the reduction reflects a broader cooling in the housing market that shows no immediate signs of reversal. The industry is currently witnessing a thinning pool of active residential projects, leading to a surplus in inventory for some suppliers while others scale back production to align with the cooling demand. This trend is particularly evident in regions that previously saw high growth, where the sudden shift in buyer behavior has left many builders with unfinished inventory and fewer prospective buyers. The contraction represents a significant hurdle for companies that are heavily reliant on the high-volume shingle market.
Economic headwinds have severely impacted builder confidence, which has plummeted to its lowest level in over a decade during the current calendar year. This pessimism is mirrored in the reroofing segment, which typically serves as a buffer during periods of low new-home construction but is currently failing to provide a boost. Spending on home improvements is expected to remain largely stagnant through late 2027, with annual growth rates hovering at a modest 1.5%. A decline in remodeling permits and flat retail sales for building materials indicate that homeowners are delaying major roof replacements in favor of essential maintenance or postponing projects entirely. To combat this slump, many builders have resorted to aggressive sales incentives, yet these measures have done little to offset the rising costs of energy and raw materials that continue to squeeze the residential pipeline. This stagnation across both new builds and renovations has created a uniquely difficult environment for shingle producers.
Robust Growth within the Nonresidential Market
In sharp contrast to the residential struggle, the nonresidential roofing sector is experiencing a robust period of growth, creating a clear division within the industry. Shipments of modified bitumen, a staple for commercial low-slope roofs, rose by 17% in the third quarter alone, reaching over 10 million squares. Similarly, built-up roofing products saw a dramatic spike of 25% during the same period. This surge is supported by a significant increase in the value of commercial and industrial building starts, which have climbed by nearly 46% year-to-date. Large-scale infrastructure projects, data centers, and corporate manufacturing facilities are receiving heavy investment, shielding this part of the industry from the woes affecting residential builders. The robust demand for low-slope asphalt products indicates that institutional and corporate capital remains active, even as consumer spending cools. This strength in the commercial sector provides a necessary counterbalance, allowing diversified manufacturers to maintain overall stability despite the shingle downturn.
The divergence between residential and commercial starts highlights the importance of institutional investment in the current economic climate. While individual housing starts have faltered, the Dodge nonresidential building starts data reveals a 23.7% increase in total value through the end of the third quarter. This growth is largely concentrated in the industrial sector, where the need for new warehousing and production facilities continues to outpace the existing supply. Institutional starts, while slightly down, still represent a stable foundation for roofing contractors specializing in schools, hospitals, and government buildings. The success of these projects depends on long-term funding cycles that are less sensitive to short-term interest rate spikes than the residential mortgage market. For the roofing industry, this means that specialized products like high-performance membranes and commercial-grade insulation are becoming the primary drivers of profitability. Manufacturers who shifted their focus toward these industrial applications early in the year are now reaping the rewards of a vibrant commercial landscape.
Analyzing Regional Shifts and Strategic Conclusions
The Canadian roofing market closely mirrors the struggles found in the United States, particularly within the residential shingle category where shipment volumes have fallen sharply. In Canada, asphalt shingle shipments dropped by 12.7% in the third quarter and are down 16.7% for the year-to-date period. Interestingly, this reduction in shipments significantly outpaces the actual decline in single-detached housing starts, which fell by only 6% over the same timeframe. This discrepancy suggests that the Canadian market is being influenced by more than just a lack of new construction. Factors such as aggressive inventory management by distributors and a significant slowdown in the private reroofing sector are likely compounding the reduction in shipment volumes. The Canadian experience underscores the continental nature of these economic pressures, as high borrowing costs and inflationary pressures on building materials affect projects across the border. This alignment between the two markets indicates a synchronized cooling of residential demand that requires a unified strategic response from regional suppliers.
To navigate the complexities of 2026, manufacturers and contractors moved toward a more diversified project portfolio that prioritized the growing commercial sector. The third-quarter data confirmed that relying solely on residential shingle volume was no longer a viable strategy for maintaining consistent growth. Industry leaders focused on improving efficiency in their supply chains and investing in specialized products that catered to the booming industrial market. By addressing the decline in builder confidence with more flexible financing options and incentivizing essential repairs, the industry sought to stabilize the residential segment while maximizing gains from nonresidential infrastructure projects. The actionable takeaway from this period was the necessity of agility in production and marketing, as the market demanded a pivot toward high-performance, low-slope applications. These strategic shifts laid the groundwork for a more resilient industry structure that better withstood the bifurcated economic conditions of the mid-decade construction landscape.