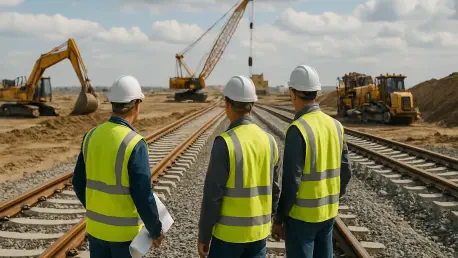
The British construction industry is currently undergoing a fundamental structural transformation as major players reassess their exposure to the increasingly volatile residential property sector. Kier Group, a cornerstone of the FTSE 250, has initiated a decisive exit from its housing division to focus on more resilient revenue streams within the national infrastructure framework. This move was primarily catalyzed by a significant twenty-five percent decline in profits within its property arm, which plummeted to nine point one million pounds amidst a cooling market and diminishing buyer demand. By systematically pulling capital out of housing, the company aims to de-risk its balance sheet against the persistent macroeconomic headwinds that have troubled the sector since the start of 2026. This strategic retreat signals a broader shift where corporate stability is being prioritized over the high-growth but high-risk potential of domestic homebuilding in an era defined by elevated interest rates and supply chain unpredictability. This focus ensures the firm remains robust and adaptable.
Corporate Strategy: Realignment in a Volatile Economy
Infrastructure Development: The Transition to Regulated Public Projects
The reallocation of resources toward government-backed projects reflects a calculated move to leverage Kier’s existing status as a strategic supplier to the public sector. The firm is now intensifying its focus on critical domains such as water, energy, defense, and healthcare, where long-term contracts offer a degree of insulation from the cyclical nature of private real estate. These sectors provide a predictable pipeline of work that aligns with national security and public service requirements, ensuring more consistent cash flows through 2028 and beyond. Unlike the residential market, which is susceptible to consumer sentiment and mortgage fluctuations, infrastructure development is driven by statutory requirements and government spending commitments. This transition allowed the group to streamline its operational focus, directing engineering expertise toward complex civil projects that demand specialized technical capabilities rather than navigating the unpredictable landscape of retail housing sales across the United Kingdom.
Market Volatility: Assessing the Decline in Residential Demand
The broader economic environment has created significant hurdles for traditional housebuilders, with rising supply costs and high mortgage rates dampening the enthusiasm of potential homeowners. Geopolitical conflicts in the Middle East have further strained global supply chains, contributing to the first annual drop in United Kingdom house prices in nearly three years. As a result, the average deposit required for a new home has surged by over eighteen thousand pounds, pricing out a substantial segment of the workforce. Other industry participants, such as MJ Gleeson, have mirrored this trend of retrenchment by reporting pre-tax losses and implementing significant dividend cuts to protect their liquidity. This cooling effect has forced a realization among contractors that the residential sector’s previous growth trajectory is no longer sustainable without substantial state intervention. Consequently, firms are choosing to pivot away from speculative developments in favor of regulated assets that promise more secure returns.
Market Sustainability: Actionable Insights for Industry Growth
Industry leaders recognized that bridging the gap between government housing targets and market realities required a multi-faceted approach involving both fiscal policy and planning reform. It became clear that housebuilders needed to advocate for targeted interventions, such as refreshed help-to-buy schemes or adjustments to stamp duty, to restore affordability for first-time buyers who faced an average deposit increase of over eighteen thousand pounds. Stakeholders focused on developing more efficient construction methodologies to offset rising supply costs that were further exacerbated by geopolitical tensions in the Middle East. By aligning corporate strategy with the 1.5 million home delivery goal, the sector sought to create a more resilient environment where public infrastructure and private housing could coexist sustainably. Moving forward, the most successful entities prioritized financial agility and deep partnerships with the public sector to mitigate the risks inherent in the domestic property market while maintaining a steady project pipeline.